




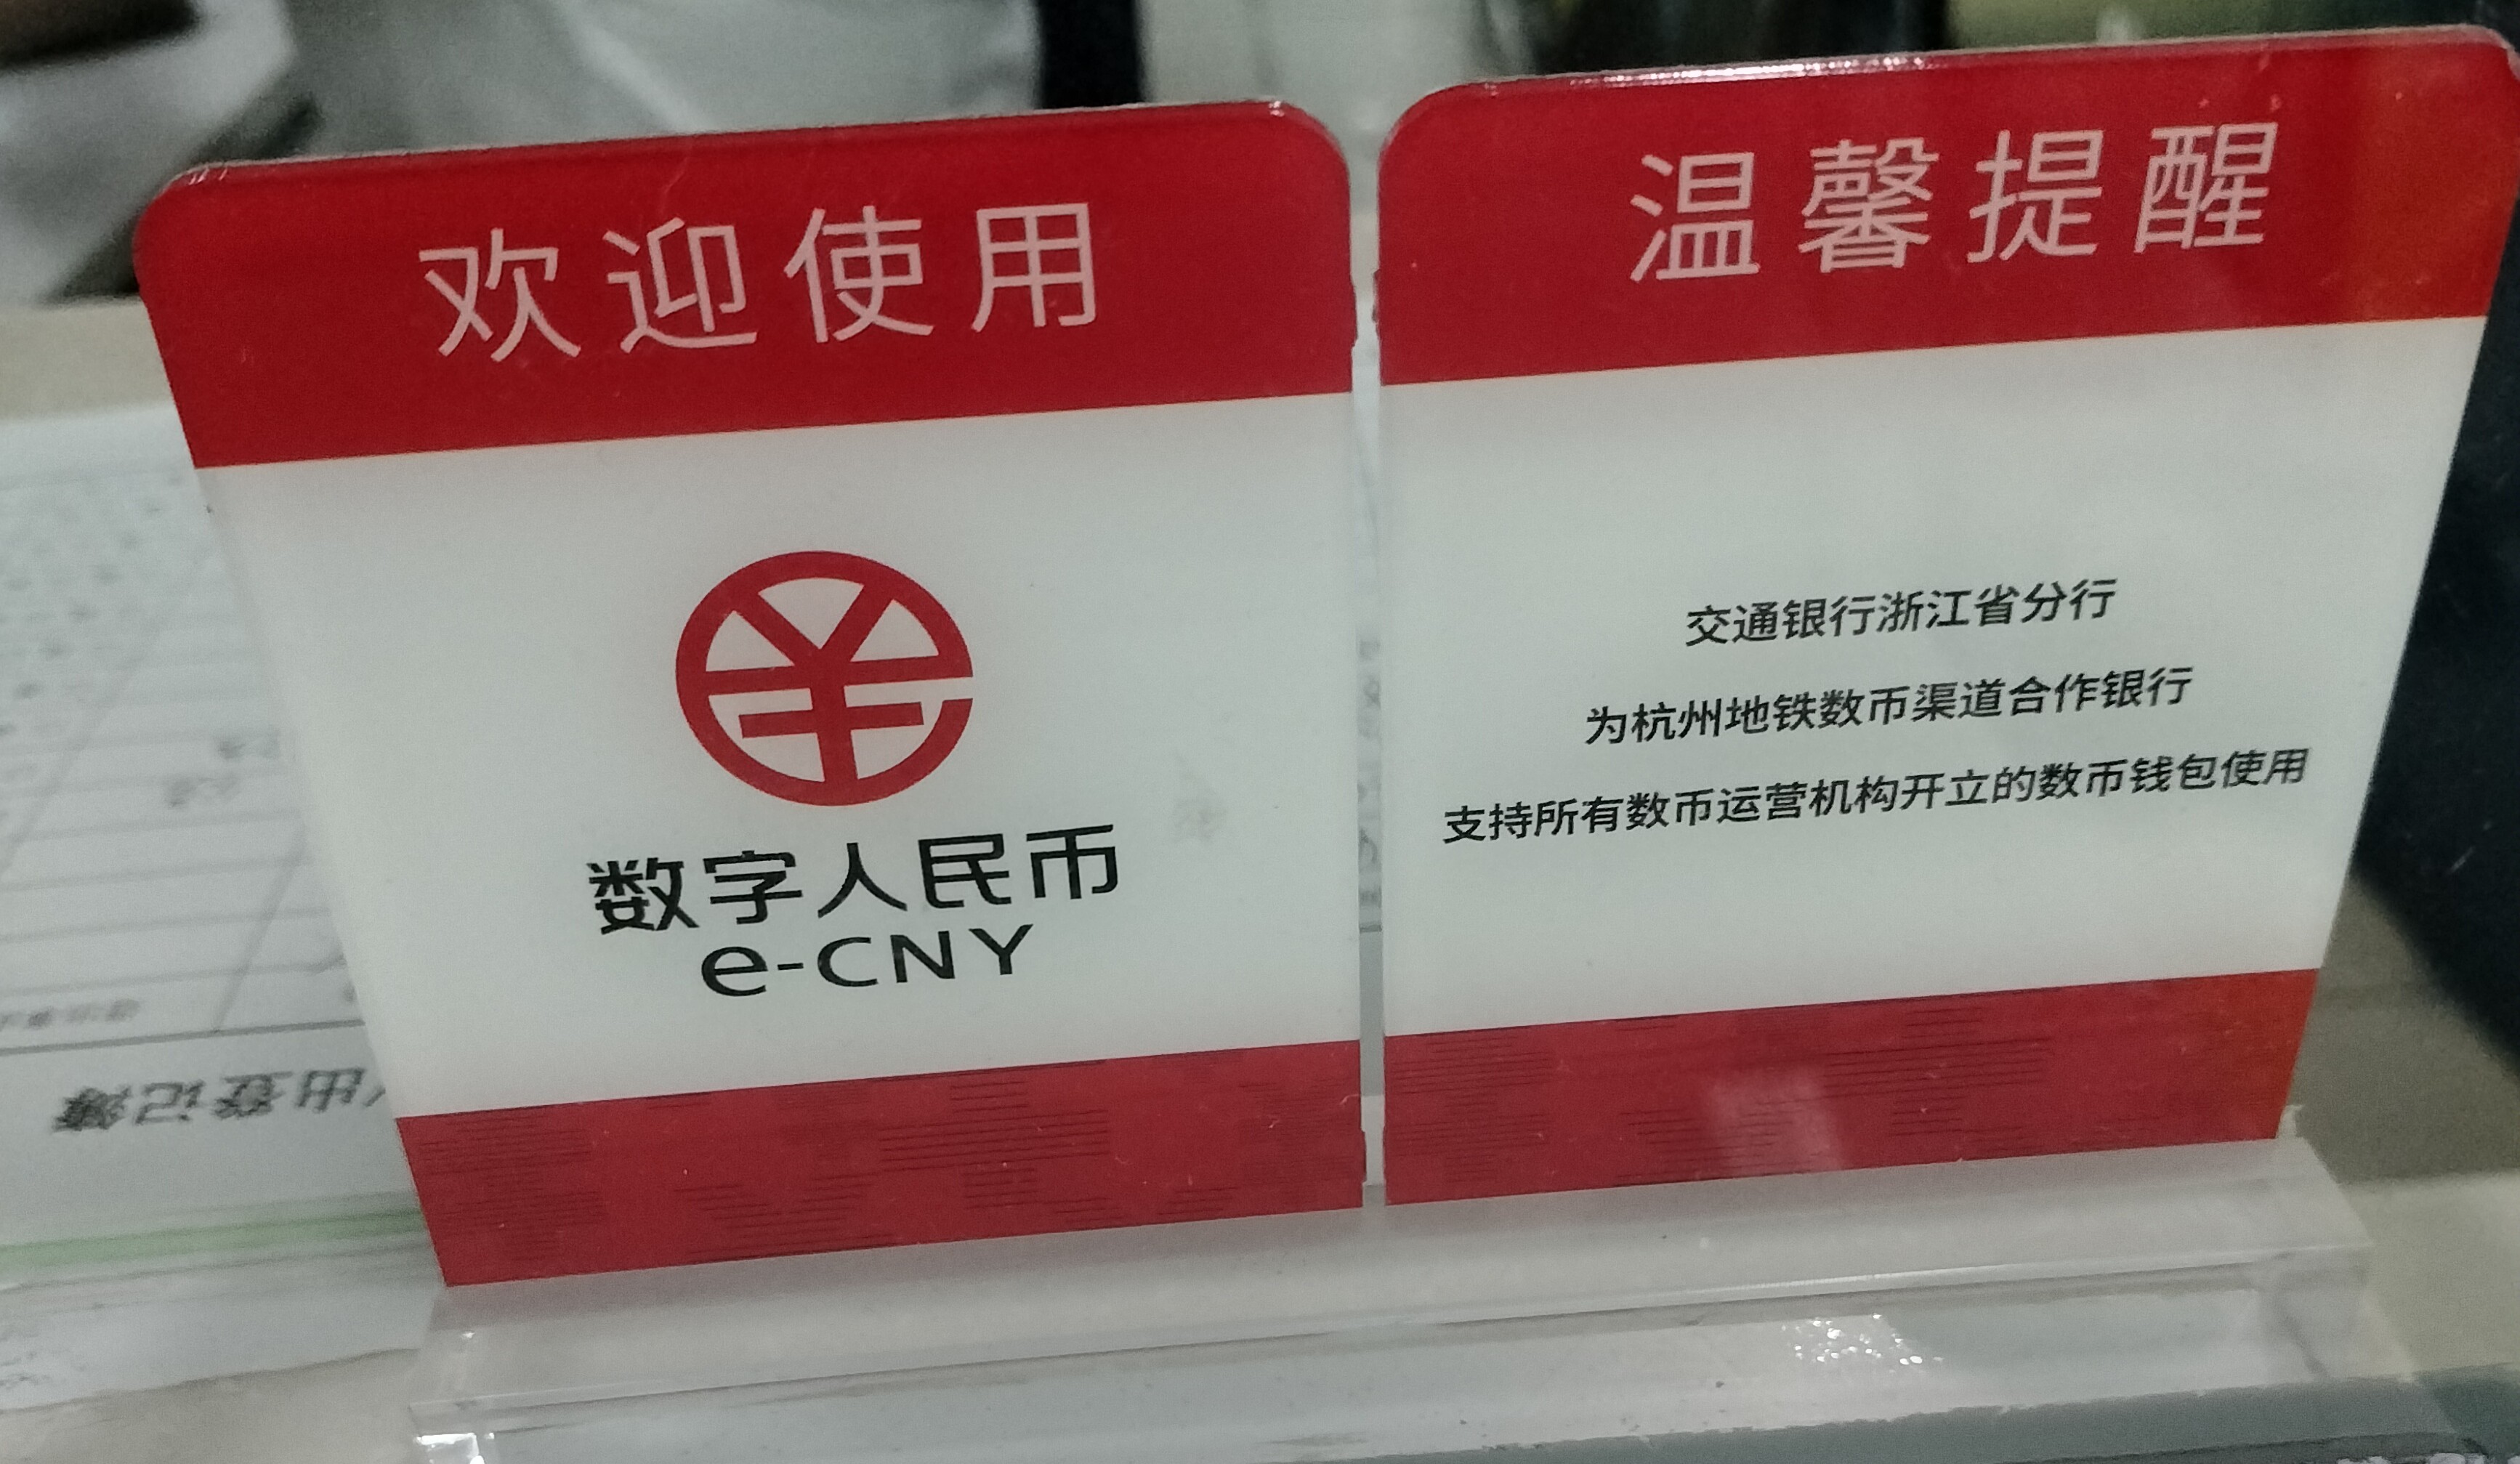
Central Bank Digital Currency
A Central Bank Digital Currency (CBDC) is a digital version of an official currency, created by a central bank rather than by private companies. Unlike cryptocurrencies such as Bitcoin, CBDCs are issued by a state and may work alongside physical cash. As of 2024, the Bahamas, Jamaica, and Nigeria have launched CBDCs, and 134 countries are researching their own versions while other jurisdictions, such as Florida, have banned CBDCs citing privacy concerns.
The concept of a CBDC has been gaining traction in recent years, with many central banks exploring the potential benefits and risks of issuing a digital currency. A CBDC could provide a fast, secure, and efficient way to conduct transactions, potentially reducing the need for physical cash and increasing financial inclusion. However, the development and implementation of a CBDC also raise important questions about privacy, security, and the potential impact on traditional banking systems.
One of the key advantages of a CBDC is its potential to increase financial inclusion, particularly in countries where access to traditional banking services is limited. A CBDC could provide a digital alternative to physical cash, allowing individuals to store and transfer value electronically. This could be particularly beneficial for individuals who do not have access to traditional banking services, such as the unbanked or underbanked populations in developing countries.
However, the development and implementation of a CBDC also raise important questions about privacy and security. A CBDC would require the collection and storage of sensitive personal and financial information, which could potentially be vulnerable to cyber attacks or data breaches. Additionally, the use of a CBDC could potentially erode the anonymity of physical cash, which is a key feature of traditional currency.
History
The concept of a CBDC has been around for several decades, but it has gained significant attention in recent years. In 2014, the Bank of England published a report on the potential for a CBDC, highlighting the potential benefits and risks of issuing a digital currency. Since then, many central banks have explored the concept of a CBDC, with some launching pilot projects or conducting feasibility studies.
In 2020, the Bahamas became the first country to launch a CBDC, known as the Sand Dollar. The Sand Dollar is a digital version of the Bahamian dollar, which can be used for transactions and stored in digital wallets. The launch of the Sand Dollar was seen as a significant milestone in the development of CBDCs, and it has been followed by the launch of CBDCs in Jamaica and Nigeria.
Mechanism
A CBDC would work similarly to traditional currency, but with some key differences. A CBDC would be issued by a central bank, which would create and manage the digital currency. The CBDC would be stored in digital wallets, which would be linked to a user's bank account or other financial institution. Transactions would be conducted electronically, using a secure and efficient payment system.
One of the key features of a CBDC is its potential to use distributed ledger technology (DLT), such as blockchain. DLT would allow for secure and transparent transactions, reducing the risk of cyber attacks or data breaches. Additionally, DLT would enable the creation of a decentralized and tamper-proof record of transactions, which would be beneficial for financial institutions and regulators.
Applications
A CBDC could have a range of applications, from increasing financial inclusion to improving the efficiency of payment systems. A CBDC could provide a fast and secure way to conduct transactions, potentially reducing the need for physical cash and increasing the use of digital payments. Additionally, a CBDC could provide a new channel for central banks to implement monetary policy, such as setting interest rates or implementing quantitative easing.
A CBDC could also have significant implications for the financial sector, particularly for traditional banking systems. A CBDC could potentially disrupt the traditional banking model, by providing a new and more efficient way to conduct transactions. This could lead to a reduction in the use of traditional banking services, potentially impacting the profitability of financial institutions.
Criticism and Controversy
The development and implementation of a CBDC have raised significant concerns about privacy and security. A CBDC would require the collection and storage of sensitive personal and financial information, which could potentially be vulnerable to cyber attacks or data breaches. Additionally, the use of a CBDC could potentially erode the anonymity of physical cash, which is a key feature of traditional currency.
Some jurisdictions, such as Florida, have banned CBDCs citing privacy concerns. This has raised questions about the potential impact of a CBDC on individual freedoms and the right to financial privacy. Additionally, the development and implementation of a CBDC have raised concerns about the potential for central banks to exert too much control over the financial system.
Future Developments
The development and implementation of a CBDC are ongoing, with many central banks exploring the concept of a digital currency. In 2024, the International Monetary Fund (IMF) published a report on the potential for CBDCs, highlighting the potential benefits and risks of issuing a digital currency. The report noted that CBDCs could provide a fast, secure, and efficient way to conduct transactions, but also raised concerns about privacy and security.
As the development and implementation of a CBDC continue, it is likely that we will see significant advancements in the technology and infrastructure required to support a digital currency. This could include the use of DLT, such as blockchain, to secure and transparent transactions. Additionally, we may see the development of new payment systems and infrastructure, such as digital wallets and payment terminals.


